A familiar insurance card does not guarantee familiar costs next year. Your premium may change, a prescription may become more expensive, or your pharmacy may no longer offer the lowest copayment.
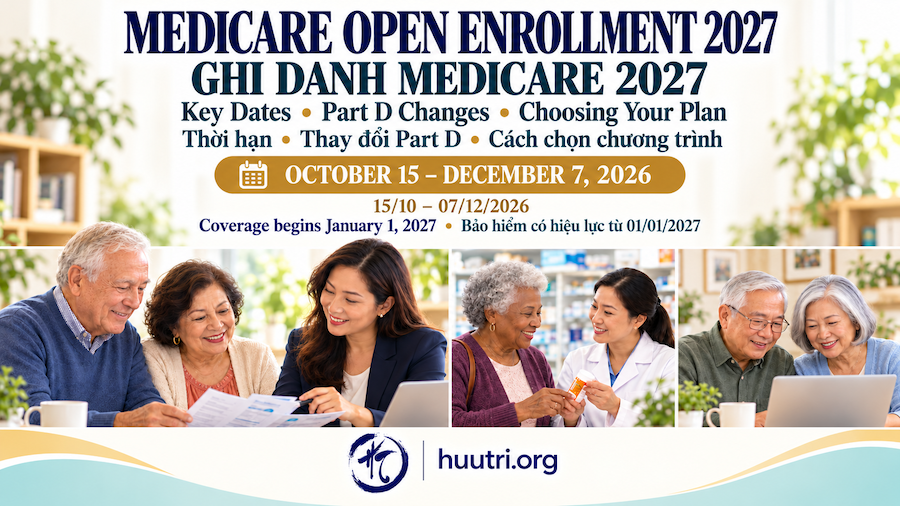
Medicare Open Enrollment begins October 15 and ends December 7, 2026. Changes made during this period take effect January 1, 2027. For older adults and family caregivers, this is an opportunity to review coverage—even when the current plan has worked well. Medicare
 What can you change?
During Open Enrollment, eligible beneficiaries can:
- Join, switch, or drop a stand-alone Part D prescription drug plan.
- Switch from one Medicare Advantage plan to another.
- Move from Original Medicare to Medicare Advantage.
- Leave Medicare Advantage and return to Original Medicare, adding a separate drug plan if needed.
Your enrollment request must reach the plan by December 7. First-time enrollment in Medicare Parts A and B follows separate rules. Medicare
If your current plan continues and you want to keep it, you generally do not have to enroll again. However, review notices about changes or discontinued coverage. CMS
Part D and stand-alone drug plans: What is the difference?
Part D is Medicare prescription drug coverage. A stand-alone drug plan is one way to receive it.
| Your Medicare coverage | How prescription coverage generally works |
| Original Medicare, Parts A and B | Add a separate Part D prescription drug plan, also called a PDP. |
| Original Medicare with Medigap, such as Plan G or Plan N | You generally still need a separate Part D plan for outpatient prescriptions. |
| Medicare Advantage with drug coverage, called MA-PD | Part D is included in the health plan. |
Original Medicare covers certain medications under Part A or Part B, but it does not provide comprehensive coverage for prescriptions filled at a retail pharmacy. Medigap policies sold after 2005 do not include prescription drug coverage. Medicare
Most Medicare Advantage HMOs and PPOs cannot be paired with a separate Part D plan. Check before enrolling: adding a stand-alone drug plan can cause disenrollment from certain Medicare Advantage plans. Medicare
What changes for Part D in 2027?
These national rules apply to both stand-alone Part D plans and Medicare Advantage plans that include drug coverage.
The annual out-of-pocket limit increases
The limit rises from $2,100 in 2026 to $2,400 in 2027. After reaching the applicable threshold, you pay nothing more for covered Part D drugs for the remainder of the calendar year.
This is a limit on covered Part D prescription expenses. It does not cap all Medicare spending: premiums, Part B medications, and noncovered prescriptions are outside this protection. Medicare
The maximum deductible rises to $700
The highest permitted Part D deductible increases from $615 in 2026 to $700 in 2027. Some plans have lower deductibles or none.
The deductible is not an additional charge on top of the $2,400 threshold. Qualifying deductible payments count toward that limit. Medicare
Stand-alone premiums vary by plan
CMS projects the average monthly stand-alone Part D premium will increase from $35.09 in 2026 to $36 in 2027.
That national average is not a quote for your plan or ZIP code. Your own premium may change considerably, so check your renewal documents. CMS
The temporary Part D Premium Stabilization Demonstration ends after 2026. Also, the separate 6% limit on increases in the national base beneficiary premium does not mean every individual plan’s premium increase is limited to 6%. CMS
Negotiated prices begin for 15 additional drugs
Medicare-negotiated prices for another 15 Part D drugs take effect January 1, 2027, following the first 10 drugs in 2026.
Your savings depend on your medication, your plan’s cost-sharing rules, and whether you receive Extra Help. A negotiated drug price is not necessarily the amount you pay at the pharmacy. CMS
The prescription payment option remains available
The Medicare Prescription Payment Plan lets you spread eligible out-of-pocket prescription costs across the calendar year through bills from your insurance plan.
Participation is voluntary. It can help manage monthly expenses, but it does not lower your total drug costs. Ask your plan how your payments would be calculated. Medicare
How to choose a Part D plan
Start with the medications you take, then compare plans that cover them.
- Prepare an accurate medication list. Include each drug’s name, strength, quantity, and refill frequency. Remember inhalers, insulin, eye drops, and prescriptions from specialists.
- Compare estimated annual costs. Visit Medicare.gov/plan-compare, enter your ZIP code, medications, and pharmacies, and compare premiums plus expected prescription expenses. The lowest monthly premium may not produce the lowest yearly cost. Medicare
- Check coverage requirements. Review the formulary—the covered-drug list—and each medication’s tier. Look for prior authorization, quantity limits, or step therapy, which may require trying another medication first. Medicare
- Compare pharmacies. An in-network pharmacy is not necessarily a preferred pharmacy. Preferred pharmacies may offer lower copayments. Compare convenient retail locations and mail order when appropriate. Medicare
- Read your Annual Notice of Change. Your plan should send this notice in September. It describes changes taking effect in January. Request a copy if you have not received it. Medicare
Consider this hypothetical comparison:
| Annual expense | Plan A | Plan B |
| Monthly premium | $10 | $35 |
| Premiums for 12 months | $120 | $420 |
| Estimated prescription payments, including any deductible | $900 | $300 |
| Estimated annual total | $1,020 | $720 |
Plan B costs $300 less over the year despite its higher premium. These figures illustrate the calculation; they are not actual plan quotes.
Even if you take few prescriptions, consider low-premium coverage. Going 63 consecutive days or more without Part D or other creditable drug coverage after your initial enrollment period can lead to an ongoing late-enrollment penalty. Medicare
How to choose a Medicare Advantage plan
Compare the medical coverage as carefully as the prescription benefit.
- Doctors and hospitals: Confirm that your doctors, specialists, and preferred hospital participate in the exact 2027 plan. Verify with both the insurer and providers.
- Access to care: Review referrals and prior authorization. HMO and PPO rules differ.
- Medical expenses: Compare hospital stays, specialist visits, surgery, rehabilitation, and the annual maximum for covered medical services. This medical maximum is separate from Part D’s drug limit.
- Travel needs: Check routine-care coverage away from home, especially if you spend months in another state.
- Extra benefits: Read dental, vision, and hearing limits, provider restrictions, and eligibility requirements. Medicare
A $0 plan premium does not mean all care is free. You generally continue paying your Part B premium and may owe deductibles and copayments. Medicare
Before leaving Medicare Advantage for Original Medicare, check whether you can obtain the Medigap policy you want. Fall Open Enrollment does not automatically guarantee Medigap acceptance. Outside protected enrollment situations, an insurer may review your health and deny coverage. State protections vary. Medicare
Where to get free assistance
- Medicare: Call 1-800-MEDICARE (1-800-633-4227) or visit Medicare.gov. CMS
- Independent counseling: Find your State Health Insurance Assistance Program. SHIP counselors are not connected to an insurance company. Medicare
- California readers: HICAP offers free, confidential Medicare counseling at 1-800-434-0222. aging.ca.gov
- Prescription cost assistance: Check Extra Help, which can lower Part D premiums, deductibles, and prescription costs for eligible beneficiaries. Medicare
The separate January 1–March 31 Medicare Advantage Open Enrollment Period applies to people already enrolled in Medicare Advantage. It is not a general second opportunity for Original Medicare beneficiaries to switch stand-alone Part D plans. Special Enrollment Periods may apply in qualifying circumstances. Medicare
Set aside time before December 7 to compare your medications, pharmacies, doctors, and annual costs. Keep your enrollment confirmation and verify the January 1 effective date.
-Lê Nguyên Vũ-
Sources and Further Reading:
- Medicare Open Enrollment — Thời gian ghi danh Medicare
Enrollment dates, permitted coverage changes, and when new coverage begins. Medicare - Medicare Plan Finder — So sánh chương trình bảo hiểm
Compare Medicare Advantage and stand-alone Part D plans using your ZIP code, prescriptions, and pharmacies. cms.gov - Part D Costs — Chi phí bảo hiểm thuốc Part D
Explains premiums, deductibles, copayments, late-enrollment penalties, and the 2027 out-of-pocket limit. Medicare - How Drug Plans Work — Cách hoạt động của chương trình thuốc
Information about covered-drug lists, medication tiers, and coverage requirements. Medicare - Original Medicare vs. Medicare Advantage — So sánh hai lựa chọn Medicare
Compares provider access, costs, prescription coverage, and additional benefits. Medicare - CMS 2027 Premium Outlook — Thông tin lệ phí Medicare năm 2027
CMS’s September 28, 2026 announcement about projected Medicare Advantage and Part D premiums. CMS - Part D Premium Stabilization Update — Thay đổi chương trình ổn định lệ phí Part D
Explains the conclusion of the temporary demonstration after 2026 and the national base beneficiary premium. CMS - Negotiated Drug Prices for 2027 — Giá thuốc được Medicare thương lượng
Details negotiated prices for 15 additional drugs taking effect January 1, 2027. CMS - Extra Help — Chương trình trợ giúp chi phí thuốc
Eligibility and assistance with prescription drug expenses for beneficiaries with limited income and resources. Medicare - California HICAP — Tư vấn Medicare miễn phí tại California
Free, confidential Medicare counseling. Call 1-800-434-0222 to connect with a local office. ca.gov