As technology giants invest unprecedented sums in artificial intelligence, thousands of employees are being offered incentives to leave. For Americans approaching retirement—and younger workers counting on decades of employment at major technology companies—the changing workplace raises an important question: Is a well-paying corporate job still a reliable foundation for long-term financial security?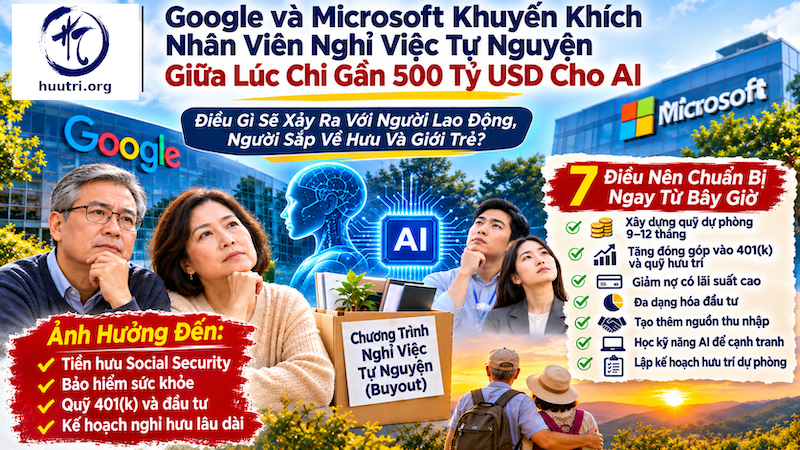
A new era in Silicon Valley: Billions for AI, fewer guarantees for workers
For decades, securing a position at Google, Microsoft, Amazon, or another major American technology company was considered a career achievement. Generous salaries, stock awards, comprehensive health insurance, 401(k) retirement plans, and opportunities for advancement made these employers especially attractive.
Many workers believed that remaining with one of these companies for 20 or 30 years could provide the financial foundation for a comfortable retirement.
But in 2026, that expectation is being challenged.
Google and Microsoft have introduced or expanded voluntary employee buyout programs while investing heavily in artificial intelligence. Microsoft announced a broad new offer in October, and Google confirmed an international expansion in November.
The financial backdrop is extraordinary.
According to a November 2026 MarketWatch report, four of America’s largest technology companies—Microsoft, Alphabet (Google’s parent company), Amazon, and Meta—spent approximately $496.7 billion on property and equipment during the first nine months of 2026, much of it supporting AI infrastructure and cloud computing.
That is nearly half a trillion dollars in just nine months. Importantly, the figure represents combined capital investment by four companies, not a $500 billion expenditure by Google and Microsoft alone, nor exclusively spending on AI.
THE SCALE OF BIG TECH INVESTMENT
$496.7 billion
Combined capital spending by Microsoft, Alphabet, Amazon and Meta in January–September 2026.
Source: MarketWatch, November 2026. Includes infrastructure and other property and equipment expenditures.
These companies are building enormous data centers, purchasing advanced AI processors, expanding cloud infrastructure, and developing increasingly sophisticated AI systems.
The investments could produce major productivity gains and new business opportunities. However, they also require substantial capital, raising pressure to control operating expenses and reconsider how companies organize their workforces.
One consequence is a growing emphasis on automation, workforce restructuring, and voluntary separation programs.
For employees in their 50s and early 60s, the timing could be particularly consequential. Losing a job or accepting a buyout shortly before retirement can disrupt years of financial planning.
Younger workers face a different challenge: the possibility that the traditional career path of joining a technology giant, advancing through its ranks, and accumulating substantial retirement benefits may become less predictable.
Microsoft offers voluntary buyouts to approximately 60,000 employees
On October 26, 2026, Microsoft announced a Voluntary Exit Offer (VEO) covering approximately 60,000 eligible employees—roughly 27% of its global workforce.
The program applies to selected employees in the United States, Canada, the United Kingdom, and India.
According to Microsoft’s official announcement, the program provides eligible workers with financial support and career-planning resources if they voluntarily leave the company. Eligibility varies by business division and job level.
Microsoft actually introduced two significant voluntary separation initiatives in 2026.
- April–May 2026: An earlier voluntary retirement program covered approximately 8,750 eligible U.S. employees. Reports indicate that more than 30% accepted.
- October 2026: A much larger voluntary exit program was announced, covering approximately 60,000 eligible workers across four countries.
The second program was not restricted to older employees. Eligible workers at level 70 and below could participate, depending on their organizations.
Microsoft has presented the program as a way to adapt its workforce to changing business needs, rather than explicitly attributing the offers to AI spending.
Nevertheless, the announcement comes as Microsoft expands its AI infrastructure investments. CBS News reported that the company expected to spend approximately $175 billion on AI infrastructure in 2026.
This distinction matters: voluntary buyouts, mandatory layoffs, and AI-related workforce restructuring are not necessarily the same thing.
Google expands voluntary buyouts to employees worldwide
On November 4, Reuters reported that Google had expanded its voluntary buyout program to employees in Canada, France, Germany, Japan, and Switzerland.
Google had previously offered similar programs to selected employees in the United States and United Kingdom.
The international expansion began in June, although details became more widely publicized in November.
In Switzerland, Reuters reported that accepted employees could receive one month’s salary for each year of service, up to a maximum of 12 months. Not every Google employee was eligible, and the company did not disclose the total number who accepted.
Google’s AI-focused operations, including DeepMind, have been excluded from previous rounds of voluntary offers.
The pattern illustrates how companies may reduce staffing in some functions while continuing to recruit specialized AI engineers and researchers.
Which other American technology companies have reduced their workforces in 2026?
Google and Microsoft are not alone in restructuring. However, it is important to distinguish companies offering voluntary buyouts from those implementing layoffs or other cost-reduction programs.
| Company | Reported 2026 action | Type |
| Microsoft | Approximately 8,750 eligible for an earlier retirement program; about 60,000 eligible for October’s offer | Voluntary buyouts |
| Google (Alphabet) | Expanded buyout programs to additional countries | Voluntary buyouts |
| Amazon | Announced approximately 16,000 job cuts in January | Layoffs |
| Meta (Facebook) | Reported plans to eliminate approximately 8,000 jobs and leave other positions unfilled | Layoffs and hiring reductions |
| Oracle | Reported large-scale job reductions, with estimates reaching 30,000 positions | Layoffs and restructuring |
| Salesforce | Reported approximately 1,000 job reductions associated with AI-driven automation | Workforce reductions |
| Intel | Continued restructuring and employee severance measures | Restructuring and severance |
Sources: Computerworld’s April 2026 industry reporting and Intel’s September 2026 SEC filing. Some figures are reported estimates rather than final confirmed departures. The companies in the last five rows should not be described as having confirmed comparable voluntary buyout offers in 2026.
Computerworld+1
The distinction is particularly important for employees deciding whether to leave voluntarily.
A voluntary buyout generally allows an eligible worker to consider a separation package before making a decision. A layoff, by contrast, is employer-initiated and may involve different severance arrangements, notice requirements, and eligibility for unemployment benefits.
Neither approach automatically guarantees continued health insurance or a secure retirement.
Why employees in their 50s and early 60s face greater financial risks
Consider a 58-year-old software manager who has spent 22 years working for a major technology company.
The employee earns $180,000 annually, has accumulated $850,000 in retirement savings, owns a home with a mortgage, and plans to retire at 67.
A voluntary buyout offering 12 months of salary may initially appear attractive.
But what happens after that first year?
If the employee cannot find another comparable position for two or three years, the financial consequences could be substantial.
- Losing high-paying employment during peak earning years
Workers in their 50s often earn some of the highest salaries of their careers. These are also the years when many people make their largest retirement contributions.
Losing employment at 58 instead of 65 could mean losing seven years of earnings, employer retirement contributions, and potential investment growth.
Although age discrimination is illegal, older job seekers may encounter challenges finding positions with comparable compensation, especially when their specialized experience does not align with newer technologies.
- Retirement savings may need to last longer
Someone who planned to retire at 67 but stops working at 58 may need to fund nine additional years before the intended retirement date.
That can dramatically alter a financial plan.
For example, an individual spending $6,000 monthly would need $72,000 annually before taxes.
Without replacement income, even a substantial severance package could disappear faster than expected.
- Health insurance becomes a major concern
Most Americans become eligible for Medicare at age 65.
A worker who accepts a buyout at 58 could face seven years of obtaining health coverage independently.
Options may include a spouse’s employer plan, COBRA continuation coverage, or an Affordable Care Act marketplace policy.
COBRA can be expensive because the former employee may need to pay the full insurance premium, plus an administrative charge. Federal COBRA continuation is generally limited to 18 months for a termination-of-employment qualifying event, although extensions or state rules may apply.
For workers already approaching 65, Medicare enrollment deadlines require special attention. COBRA is not treated as active-employment coverage for Medicare Part B enrollment purposes.
- Social Security benefits could be lower than expected
Social Security retirement benefits can begin at age 62, but claiming before full retirement age permanently reduces the monthly benefit compared with waiting until full retirement age.
For people born in 1960 or later, full retirement age is 67.
Someone who stops working early may also lose the opportunity to replace lower-earning years in the 35-year earnings history used to calculate benefits.
A buyout at 60 does not automatically mean someone should claim Social Security at 62.
The decision should account for health, household income, savings, taxes, and expected longevity.
- Company stock can create a double financial risk
Technology employees often accumulate company shares through restricted stock units (RSUs), employee stock purchase plans, and stock options.
This creates a concentration risk: the same employer may provide both the worker’s paycheck and a significant portion of retirement wealth.
If the company experiences a business downturn, the employee could lose a job while also seeing the value of company shares decline.
Employees considering a buyout should examine unvested stock awards, option exercise deadlines, and tax consequences before signing an agreement.
What about younger employees who planned to retire from Big Tech?
The implications extend beyond older workers.
For decades, young engineers, programmers, financial analysts, and business graduates competed for positions at technology companies offering generous compensation and benefits.
Many expected a familiar career trajectory: join a major employer in their 20s, receive regular promotions, accumulate stock, contribute to a 401(k), and eventually retire with substantial savings.
That path remains possible, but it should no longer be treated as guaranteed.
AI is changing how companies perform software development, customer support, data analysis, marketing, and administrative tasks.
Some traditional positions may shrink or change, while new opportunities emerge in AI engineering, cybersecurity, data-center operations, infrastructure management, and AI governance.
The lesson for younger employees is not to abandon technology careers. It is to avoid building a retirement strategy around the assumption of uninterrupted employment with one company.
A 28-year-old worker may change employers several times over a 35- or 40-year career.
Retirement savings must therefore remain portable, diversified, and independent of any single employer’s future.
Seven financial adjustments Americans should consider starting now
- Build a larger emergency fund
A traditional emergency fund covering three to six months of essential expenses may be insufficient for workers facing a prolonged job search.
Workers in their 50s, particularly those in highly specialized or senior positions, may wish to target nine to twelve months of essential expenses, depending on household income stability.
For example, a household with $5,000 in monthly essential expenses would need $45,000–$60,000 to cover nine to twelve months.
Keep these reserves in accessible, relatively stable accounts rather than speculative investments.
- Increase retirement contributions while employed
The IRS allows additional retirement contributions for workers age 50 and older.
For 2026, the employee contribution limits for most traditional 401(k) plans are:
| Age | Maximum employee 401(k) contribution |
| Under 50 | $24,500 |
| 50–59 | $32,500 |
| 60–63 | $35,750 |
| 64 and older | $32,500 |
These amounts include applicable catch-up contributions and assume the plan permits them. Employer contributions are separate.
The special higher catch-up amount for ages 60–63 creates an opportunity to accelerate retirement savings during the final working years. Certain higher-income employees must make catch-up contributions on a Roth basis beginning in 2026.
Workers should also review IRA eligibility, employer matching, and whether traditional or Roth contributions are more appropriate for their tax circumstances.
- Reduce expensive debt before retirement
A generous severance package may provide temporary financial flexibility, but using it without a plan can create problems.
Prioritize high-interest credit cards and other expensive debts. Review mortgage obligations, automobile payments, and discretionary spending.
Paying off a low-interest mortgage early is not always the best choice if it leaves insufficient cash for living expenses or health insurance.
The goal is to lower unavoidable monthly expenses while preserving adequate liquidity.
- Diversify retirement investments
Employees should avoid relying excessively on their employer’s stock.
A diversified retirement portfolio may include broad-market stock funds, bonds, cash reserves, and other investments appropriate to the investor’s age and risk tolerance.
Someone nearing retirement should consider whether the portfolio could withstand a substantial stock-market decline during the first few years of retirement.
Diversification does not eliminate investment losses, but it reduces dependence on a single company’s performance.
- Develop additional sources of income
Workers should consider building income opportunities that do not depend entirely on one employer.
Possible examples include consulting, professional training, freelance work, part-time employment, or a carefully evaluated small business.
For older technology professionals, decades of experience in management, operations, finance, cybersecurity, and software systems may remain valuable to smaller businesses that cannot afford full-time executives.
However, starting a business requires capital and involves risk. Retirement funds should not be invested in a new venture without careful planning.
- Continue learning AI-related skills
AI literacy is becoming relevant across many professions.
Workers do not necessarily need to become AI engineers. They may benefit from learning how to use AI tools to improve productivity, evaluate outputs, manage workflows, protect sensitive information, and support business decisions.
Experienced employees who combine industry knowledge with current technology skills may have more career options than those relying exclusively on their existing job descriptions.
For younger workers, continuous professional development should be treated as a long-term career investment.
- Prepare a retirement backup plan
Every worker approaching retirement should evaluate at least three possible scenarios:
- Planned retirement: Continue working until the intended retirement age.
- Early separation: Lose employment or accept a buyout several years earlier.
- Reduced-income employment: Transition to consulting or part-time work before full retirement.
Each scenario should account for savings, taxes, health insurance, Social Security timing, housing costs, and inflation.
A retirement plan that only works if employment continues uninterrupted until age 67 is vulnerable to unexpected change.
Before accepting a buyout: Five questions every employee should ask
A voluntary buyout can be financially beneficial for someone already prepared to retire or transition to another career. But an attractive offer is not necessarily a good financial decision.
Before accepting, employees should determine:
- How much money will I actually receive? Calculate the severance amount after estimated taxes, and determine whether unused vacation, bonuses, and other compensation are included.
- What happens to my health insurance? Confirm when employer coverage ends and how much replacement coverage will cost.
- What happens to my 401(k) and company stock? Review vesting, stock-option deadlines, retirement-plan distributions, and rollover options. Employees who separate during or after the year they turn 55 may qualify for a special exception to the 10% early-withdrawal tax on distributions from that employer’s qualifying retirement plan; this exception generally does not apply to IRAs.
- Can I afford to remain unemployed for 12–24 months? Calculate essential expenses and available cash without assuming immediate reemployment.
- Am I giving up legal rights? Employees age 40 and older have special protections when waiving federal age-discrimination claims. Depending on the agreement and program, federal rules generally require at least 21 or 45 days to consider a waiver and seven days to revoke it. An employment attorney can help evaluate the agreement.
How much could regular saving make a difference?
For younger employees, starting early can help compensate for career uncertainty.
Consider someone who invests $500 per month into a diversified retirement portfolio for 30 years.
Illustrative retirement savings calculator
Monthly investment
$500
Years invested
30 years
Assumed annual return
6%
PROJECTED ACCOUNT VALUE
$502,258
Contributions: $180,000
Growth: $322,258
Illustration assumes monthly contributions at month-end and a constant annualized return compounded monthly. Excludes taxes, fees and inflation. Actual investment returns fluctuate and are not guaranteed.
The advantage of beginning early is that investment growth has more time to compound. But workers approaching retirement can also make meaningful improvements by increasing savings, reducing debt, and avoiding unnecessary withdrawals.
The bigger lesson: Your retirement should not depend on one employer
The technology industry’s transformation offers a lesson that extends well beyond Silicon Valley.
A successful company can continue generating substantial profits, expanding into new markets, and investing billions of dollars while simultaneously reducing employment in certain departments.
Corporate growth and individual job security are not always the same thing.
Artificial intelligence may create valuable new careers and improve productivity across the economy. It may also eliminate or substantially change some existing jobs. The long-term employment effects remain uncertain.
For workers in their 50s and 60s, financial independence increasingly means being prepared for the possibility of leaving the workforce earlier than expected.
For younger generations, it means saving consistently, keeping professional skills current, and avoiding excessive dependence on employer stock or a single career path.
The most important retirement benefit is not simply the one a company offers. It is the financial security an individual builds and can carry from one stage of life to the next.
As Google, Microsoft, and other technology giants invest in the future of artificial intelligence, American workers should also be investing in their own future—one that remains financially sustainable even when the workplace changes.
-Nguyễn Bách Khoa-
Sources and further reading
- Reuters — Google expands voluntary buyout offers, November 4, 2026
- Microsoft Official Blog — Introducing a Voluntary Exit Offer, October 26, 2026
- CBS News — Microsoft’s 60,000-worker buyout program
- MarketWatch — Big Tech’s $500 billion capital spending spree
- Internal Revenue Service — 2026 retirement contribution limits
- U.S. Equal Employment Opportunity Commission — Severance agreement protections
- Social Security Administration — Medicare special enrollment rules
Editorial note: This article is intended for general educational purposes for HuuTri.org readers. Financial and retirement decisions should be evaluated according to individual circumstances, with qualified tax, financial, or legal advice where appropriate.