Medicare is broad protection, not complete protection
One of the most costly retirement mistakes is assuming that Medicare covers every service an older adult may need. It does not. Even when a service is covered, deductibles and coinsurance may remain.
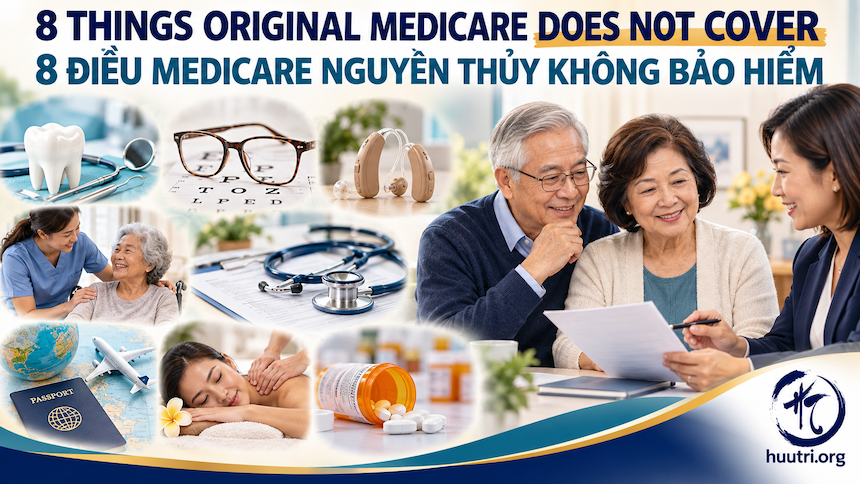
Here are eight major gaps Huutri.org readers should plan for.
 1. Most routine dental care
Original Medicare generally does not cover cleanings, fillings, crowns, dentures, implants, or most routine extractions. It may cover limited dental services closely connected with certain covered medical treatment, but ordinary dental restoration remains a major gap.
Plan ahead: Compare Medicare Advantage dental limits, stand-alone coverage, community clinics, and a dedicated dental savings fund.
2. Routine eye exams and most eyeglasses
Original Medicare does not cover routine refractions for eyeglasses or contact lenses. It does cover certain medical eye services and one pair of standard eyeglasses or contacts after each covered cataract surgery that implants an intraocular lens.
Plan ahead: Separate routine vision allowances from medical eye coverage when comparing plans.
3. Hearing aids and fitting exams
Part B may cover medically necessary diagnostic hearing and balance tests, but Original Medicare does not cover hearing aids or exams performed solely to fit them.
Plan ahead: Compare plan allowances, vendor restrictions, warranties, follow-up service, and over-the-counter options where appropriate.
4. Long-term custodial care
Medicare does not pay for long-term care when the main need is help with activities of daily living, such as bathing, dressing, eating, toileting, or supervision.
Medicare may cover limited skilled nursing facility or home health services when strict medical and eligibility conditions are met. It does not become unlimited nursing-home, assisted-living, or round-the-clock home-care coverage.
Plan ahead: Consider personal savings, family support, long-term-care insurance, Medicaid planning with qualified professional advice, and local aging services before a crisis.
5. Routine physical examinations
Medicare covers the one-time “Welcome to Medicare” preventive visit and yearly Wellness visits, but these are not traditional comprehensive physical examinations. Additional diagnostic work or discussion of new medical problems may generate charges.
Plan ahead: Ask the office how the appointment will be coded and whether additional services will be billed.
6. Most care outside the United States
Original Medicare generally does not cover health care outside the United States, with limited exceptions involving certain emergencies and geographic circumstances.
Some Medigap policies and Medicare Advantage plans offer limited foreign-travel emergency coverage. Limits, deductibles, time periods, and lifetime maximums may apply.
Plan ahead: Frequent travelers should compare overseas emergency benefits and consider travel medical insurance and medical evacuation coverage.
7. Cosmetic, massage, and most concierge services
Original Medicare generally does not cover cosmetic surgery unless it is needed because of an accidental injury or to improve the function of a malformed body part. It does not cover massage therapy. Concierge membership or retainer fees are also generally not covered, even when Medicare may separately cover eligible medical services furnished by a participating clinician.
Plan ahead: Ask for a written breakdown of covered medical services and noncovered membership or elective charges.
8. Outpatient prescriptions without Part D—and care from opted-out providers
Original Medicare does not provide broad outpatient prescription coverage by itself. Part B covers certain drugs in limited circumstances, but most retail prescriptions require Part D or other drug coverage.
Medicare also generally does not pay for services from a doctor who has formally opted out of Medicare, except in limited emergency or urgent situations. A private contract may make the patient responsible for the full charge.
Plan ahead: Keep creditable drug coverage, check every medicine against the formulary, and confirm a provider’s Medicare status before nonemergency care.
“Not covered” is different from “not paid in full”
Original Medicare usually pays 80 percent of the Medicare-approved amount for covered Part B services after the deductible. The remaining 20 percent is not an uncovered service; it is the beneficiary’s coinsurance. Original Medicare also has no yearly out-of-pocket maximum.
Medigap may help with certain Part A and Part B cost sharing, but it generally does not fill the routine dental, vision, hearing, or long-term-care gaps described above. Medicare Advantage may offer extra benefits and has a yearly medical out-of-pocket limit, but networks, prior authorization, copayments, and exclusions apply.
Protect yourself before receiving a service
Ask four questions:
- Is this service covered by Medicare for my diagnosis and circumstances?
- Does the provider accept assignment or participate in my plan network?
- Is prior authorization required?
- What is my estimated total cost?
Original Medicare beneficiaries may receive an Advance Beneficiary Notice when a provider believes Medicare may not pay. The notice should describe the service and estimated cost. It is not simply another form to sign without reading.
If a claim is denied, read the Medicare Summary Notice or plan Explanation of Benefits and follow the appeal instructions. A denial is not always the final answer.
Bottom line
Medicare protects retirees from many medical expenses, but it is not designed to pay for every health-related need. The safest retirement plan includes money and coverage for the gaps—not just the services shown on a Medicare card.
-Nguyễn Bách Khoa-
Editorial Note:
Medicare is not one policy, one bill, or one decision. It is a collection of benefits, deadlines, costs, and private-plan choices that can affect a retiree for years. This eight-part Huutri.org series is designed to help older adults, spouses, adult children, and caregivers understand the questions they should ask before enrolling or receiving care.
The figures in this series are for 2026. Medicare costs and private-plan benefits can change each year. Readers should verify current information at Medicare.gov, Social Security, their plan, or their local State Health Insurance Assistance Program (SHIP).
This series is for general education. It is not medical, legal, tax, or insurance advice.
Sources and further reading
- Medicare: What Original Medicare does not cover
- Medicare: Travel outside the United States
- Medicare: Hearing aids
- Medicare: Routine eye exams
- Medicare: Dental services
- Medicare & You handbook
Part 8: Eight Important Things Original Medicare Does Not Cover
Medicare is broad protection, not complete protection
One of the most costly retirement mistakes is assuming that Medicare covers every service an older adult may need. It does not. Even when a service is covered, deductibles and coinsurance may remain.
Here are eight major gaps Huutri.org readers should plan for.
1. Most routine dental care
Original Medicare generally does not cover cleanings, fillings, crowns, dentures, implants, or most routine extractions. It may cover limited dental services closely connected with certain covered medical treatment, but ordinary dental restoration remains a major gap.
Plan ahead: Compare Medicare Advantage dental limits, stand-alone coverage, community clinics, and a dedicated dental savings fund.
2. Routine eye exams and most eyeglasses
Original Medicare does not cover routine refractions for eyeglasses or contact lenses. It does cover certain medical eye services and one pair of standard eyeglasses or contacts after each covered cataract surgery that implants an intraocular lens.
Plan ahead: Separate routine vision allowances from medical eye coverage when comparing plans.
3. Hearing aids and fitting exams
Part B may cover medically necessary diagnostic hearing and balance tests, but Original Medicare does not cover hearing aids or exams performed solely to fit them.
Plan ahead: Compare plan allowances, vendor restrictions, warranties, follow-up service, and over-the-counter options where appropriate.
4. Long-term custodial care
Medicare does not pay for long-term care when the main need is help with activities of daily living, such as bathing, dressing, eating, toileting, or supervision.
Medicare may cover limited skilled nursing facility or home health services when strict medical and eligibility conditions are met. It does not become unlimited nursing-home, assisted-living, or round-the-clock home-care coverage.
Plan ahead: Consider personal savings, family support, long-term-care insurance, Medicaid planning with qualified professional advice, and local aging services before a crisis.
5. Routine physical examinations
Medicare covers the one-time “Welcome to Medicare” preventive visit and yearly Wellness visits, but these are not traditional comprehensive physical examinations. Additional diagnostic work or discussion of new medical problems may generate charges.
Plan ahead: Ask the office how the appointment will be coded and whether additional services will be billed.
6. Most care outside the United States
Original Medicare generally does not cover health care outside the United States, with limited exceptions involving certain emergencies and geographic circumstances.
Some Medigap policies and Medicare Advantage plans offer limited foreign-travel emergency coverage. Limits, deductibles, time periods, and lifetime maximums may apply.
Plan ahead: Frequent travelers should compare overseas emergency benefits and consider travel medical insurance and medical evacuation coverage.
7. Cosmetic, massage, and most concierge services
Original Medicare generally does not cover cosmetic surgery unless it is needed because of an accidental injury or to improve the function of a malformed body part. It does not cover massage therapy. Concierge membership or retainer fees are also generally not covered, even when Medicare may separately cover eligible medical services furnished by a participating clinician.
Plan ahead: Ask for a written breakdown of covered medical services and noncovered membership or elective charges.
8. Outpatient prescriptions without Part D—and care from opted-out providers
Original Medicare does not provide broad outpatient prescription coverage by itself. Part B covers certain drugs in limited circumstances, but most retail prescriptions require Part D or other drug coverage.
Medicare also generally does not pay for services from a doctor who has formally opted out of Medicare, except in limited emergency or urgent situations. A private contract may make the patient responsible for the full charge.
Plan ahead: Keep creditable drug coverage, check every medicine against the formulary, and confirm a provider’s Medicare status before nonemergency care.
“Not covered” is different from “not paid in full”
Original Medicare usually pays 80 percent of the Medicare-approved amount for covered Part B services after the deductible. The remaining 20 percent is not an uncovered service; it is the beneficiary’s coinsurance. Original Medicare also has no yearly out-of-pocket maximum.
Medigap may help with certain Part A and Part B cost sharing, but it generally does not fill the routine dental, vision, hearing, or long-term-care gaps described above. Medicare Advantage may offer extra benefits and has a yearly medical out-of-pocket limit, but networks, prior authorization, copayments, and exclusions apply.
Protect yourself before receiving a service
Ask four questions:
- Is this service covered by Medicare for my diagnosis and circumstances?
- Does the provider accept assignment or participate in my plan network?
- Is prior authorization required?
- What is my estimated total cost?
Original Medicare beneficiaries may receive an Advance Beneficiary Notice when a provider believes Medicare may not pay. The notice should describe the service and estimated cost. It is not simply another form to sign without reading.
If a claim is denied, read the Medicare Summary Notice or plan Explanation of Benefits and follow the appeal instructions. A denial is not always the final answer.
Bottom line
Medicare protects retirees from many medical expenses, but it is not designed to pay for every health-related need. The safest retirement plan includes money and coverage for the gaps—not just the services shown on a Medicare card.
-Nguyễn Bách Khoa-
Editorial Note:
Medicare is not one policy, one bill, or one decision. It is a collection of benefits, deadlines, costs, and private-plan choices that can affect a retiree for years. This eight-part Huutri.org series is designed to help older adults, spouses, adult children, and caregivers understand the questions they should ask before enrolling or receiving care.
The figures in this series are for 2026. Medicare costs and private-plan benefits can change each year. Readers should verify current information at Medicare.gov, Social Security, their plan, or their local State Health Insurance Assistance Program (SHIP).
This series is for general education. It is not medical, legal, tax, or insurance advice.
Sources and further reading