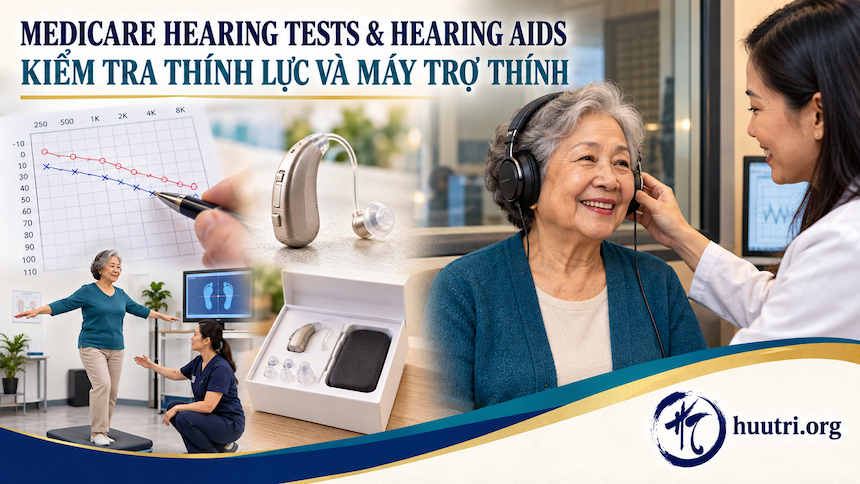
Part 6: Medicare Hearing Tests and Hearing Aids—Know the Difference
A hearing test is not always the same Medicare benefit
Hearing loss can affect conversations, safety, balance, and social connection. Yet many retirees discover that Original Medicare distinguishes among a diagnostic hearing examination, an examination to fit a hearing aid, and the hearing aid itself.
Those distinctions determine whether Medicare pays.
 What Part B can cover
Part B covers diagnostic hearing and balance examinations when a doctor or other qualified health-care provider orders them to determine whether medical treatment is needed.
Current Medicare guidance also allows a beneficiary to visit an audiologist once every 12 months without an order for certain non-acute hearing conditions, such as hearing loss that developed over many years, and for certain diagnostic services related to hearing loss treated with surgically implanted hearing devices.
After the Part B deductible, the beneficiary generally pays 20 percent of the Medicare-approved amount. An additional copayment may apply in a hospital outpatient setting.
What Original Medicare does not cover
Original Medicare does not cover:
- Hearing aids.
- Exams performed solely to fit hearing aids.
- Most routine hearing-aid maintenance, batteries, or accessories.
The beneficiary generally pays the full cost unless another insurance benefit applies.
Screening, diagnosis, and fitting are different
A brief hearing screening may indicate that hearing loss is possible. A diagnostic audiology evaluation measures the type and degree of loss and may help identify whether medical treatment is needed. A hearing-aid fitting selects and adjusts a device.
Ask the office:
- Is the service diagnostic or solely for hearing-aid fitting?
- Is an order required for my situation?
- Does the audiologist accept Medicare assignment or my plan?
- Which billing codes will be used?
- What will I owe if Medicare denies the service?
Medicare Advantage hearing benefits vary
Some Medicare Advantage plans provide a routine hearing exam, an allowance, or contracted prices for hearing aids. The benefit may be limited to particular vendors, models, technology levels, or replacement schedules.
Check:
- The exam copayment.
- The maximum plan payment per ear.
- Whether the benefit is an allowance or a discounted price.
- Approved brands and vendors.
- Trial and return periods.
- Warranty, loss, and damage coverage.
- Number of adjustment visits included.
- Battery or charger coverage.
- Replacement frequency.
Do not assume “hearing coverage” means the plan pays the full price of premium devices.
Over-the-counter hearing aids may be an option for some adults
Adults with perceived mild to moderate hearing loss can buy certain hearing aids over the counter without a prescription. They are not appropriate for every person or every degree of hearing loss. Someone with one-sided loss, ear pain, drainage, severe dizziness, sudden change, or possible severe loss should seek professional evaluation.
Compare the total value, not only the device price: professional testing, programming, follow-up adjustments, warranty, returns, and repairs can make a substantial difference.
Sudden hearing loss is urgent
Sudden hearing loss—especially in one ear—can be a medical emergency. Do not wait for a routine appointment or assume the ear is blocked. Prompt evaluation can be important for treatment.
Bottom line
Original Medicare may cover medically necessary diagnostic hearing and balance testing, but it does not cover ordinary hearing aids or exams solely for fitting them. Medicare Advantage benefits may help, but readers should examine dollar limits, vendors, and service terms before choosing a device.
-Lê Nguyên Vũ-
Editorial Note:
Medicare is not one policy, one bill, or one decision. It is a collection of benefits, deadlines, costs, and private-plan choices that can affect a retiree for years. This eight-part Huutri.org series is designed to help older adults, spouses, adult children, and caregivers understand the questions they should ask before enrolling or receiving care.
The figures in this series are for 2026. Medicare costs and private-plan benefits can change each year. Readers should verify current information at Medicare.gov, Social Security, their plan, or their local State Health Insurance Assistance Program (SHIP).
This series is for general education. It is not medical, legal, tax, or insurance advice.
Sources and further reading